How to Transfer a Pension into a Property
The UK property market can be unpredictable and somewhat daunting, especially for first-time buyers. With higher-than-average house prices, strong competition, and fluctuating interest rates, it can often feel like an uphill battle to secure a home, whether you're buying a property to live in or to rent out to tenants.
However, an often-overlooked avenue for buying a home in the UK can significantly boost your efforts: your pension.
In this article, we will explore the possibilities and potential of using your pension as a deposit for a home. While it's not exactly straightforward or linear, it could be viable for those who have built up a substantial pension pot and are seeking alternative financing options.
The Potential of Pension Funds as Property Deposits
The property market has become challenging for first-time buyers and those already on the property ladder. Rising house prices and stringent lending criteria have caused challenges for everyone trying to either save for a deposit, or upgrade from a flat or apartment to a house, and those trapped in a cycle of renting are unable to afford the initial outlay required to buy a home.
Your pension could be a valuable asset in your quest to buy a home, however. If you have accrued a respectable pension pot throughout your career, you may find it suitable to use as a house deposit. Many people who have spent time with different employers try to condense and bring together their various pensions into one single pot for ease of access and simplicity. Technically, you are allowed to buy residential property with your pension fund, including buy-to-let properties.
However, it's important to understand the complexities and potential drawbacks before making such a crucial, life-changing decision.
How Does Using a Pension for a Property Purchase Work?
There are several ways to use your pension when purchasing a property.
Cash Out Your Pension
This involves withdrawing a lump sum from your pension pot and using it as a deposit. However, it's worth noting that HMRC can impose a significant tax bill on you, and may reduce your future retirement income. Buying a house with your pension would mean it would form part of your estate, and would be subject to inheritance tax after your death, along with any investment gains under Capital Gains Tax (CGT).
Residential Property Fund
Your pension can be used to buy residential property through a Residential Property Fund. However, it's important to remember that you won't have control over which properties are invested in, should you choose this route, and you will also likely be subject to fund management fees, charges, and running costs.
Pension Linked Mortgage
A further option is to seek pension-linked mortgages from lenders, where your pension is effectively used as security for the loan. This interest-free option can potentially lower your monthly mortgage repayments, not to mention pension contributions benefiting from up to 40% tax relief for higher-rate taxpayers. However, it's important to carefully consider the terms and conditions of such loans, and always seek professional mortgage advice before committing to such a scheme.
Invest Directly in Commercial Property
You can also invest your pension funds directly in property - this is an option for those considering buying commercial real estate. You could potentially enjoy significant tax benefits if you use your pension to buy a commercial property, and you may benefit from capital appreciation and rental income. You also will not have to pay tax on any income the property may generate, as long as it's held within a self-invested personal pension (SIPP).
Invest Directly in Residential Property
Similarly, you can transfer your pension into residential property, under the Pension Schemes Act 2015. This was a popular choice among aspiring homeowners who decided to withdraw all their pensions and buy a house, although this isn't always the most viable option for homeowners nowadays. There are exceptions and costs to consider, which is why impartial advice from financial advisors and property experts is always vital.
The Pros and Cons of Using Pensions for Property
Before deciding whether to use your pension in a property transaction, it's essential to weigh up the potential advantages and considerations of doing so. It's not a decision to be taken lightly, as it could affect your financial future.
Benefits of Using Pensions for Property Purchases
- Increased purchasing power: A larger deposit can help you buy a higher value property or secure a more preferable interest rate on your mortgage, which can prove invaluable at times when costs are higher than average.
- Potential for rental income: If you invest in a property through your pension, you could generate rental income to supplement your retirement and living costs. Your responsibilities as a landlord still apply, but regular rental income can definitely be a valuable cash boost.
- Some tax benefits: Depending on the structure of your pension, you may be able to benefit from capital appreciation and tax relief, for example, on any income the property generates.
Disadvantages of Using Pensions for Property Purchases
- Tax implications: Cashing out your pension early can have significant tax implications, potentially reducing your future retirement income. You will also be subject to inheritance tax and CGT.
- High risk: As with any property purchase, there is an element of risk, including the possibility of property values declining over time. This is why some homeowners elect to keep their pensions separate from any property investments.
- Reduced flexibility: Using your pension for a property purchase can limit your future investment options and reduce your financial flexibility.
Bear these in mind before you undertake such an investment.
Why It's Important to Seek Professional Advice
Given the non-linear nature of pension-related property purchases and their complexities, it's highly recommended to seek professional advice before making any decisions. In the first instance, the UK Government has impartial information to help you plan both your pension and retirement incomes. It covers everything, from choosing a pension, planning savings to deferring or delaying payments.
With an understanding of all the available options, you can then pinpoint the most appropriate, tax-efficient and safe decisions to safeguard your assets, consider any risks, and develop a plan that aligns with your long-term financial goals.
Additionally, consulting with a reputable sales, lettings, and property management agency like Emoov can help you ascertain what properties could be worth your time and resources if you are planning to add one to your portfolio. Our friendly and knowledgeable experts are well-versed in all types of properties and can help you find ones that meet both your financial budget and long-term expectations.
Using your pension as a deposit for a property can undoubtedly be viable, but we strongly recommend proceeding with caution. Consider the potential benefits and drawbacks and always seek professional, impartial advice to ensure you make the smartest decision for your financial future.
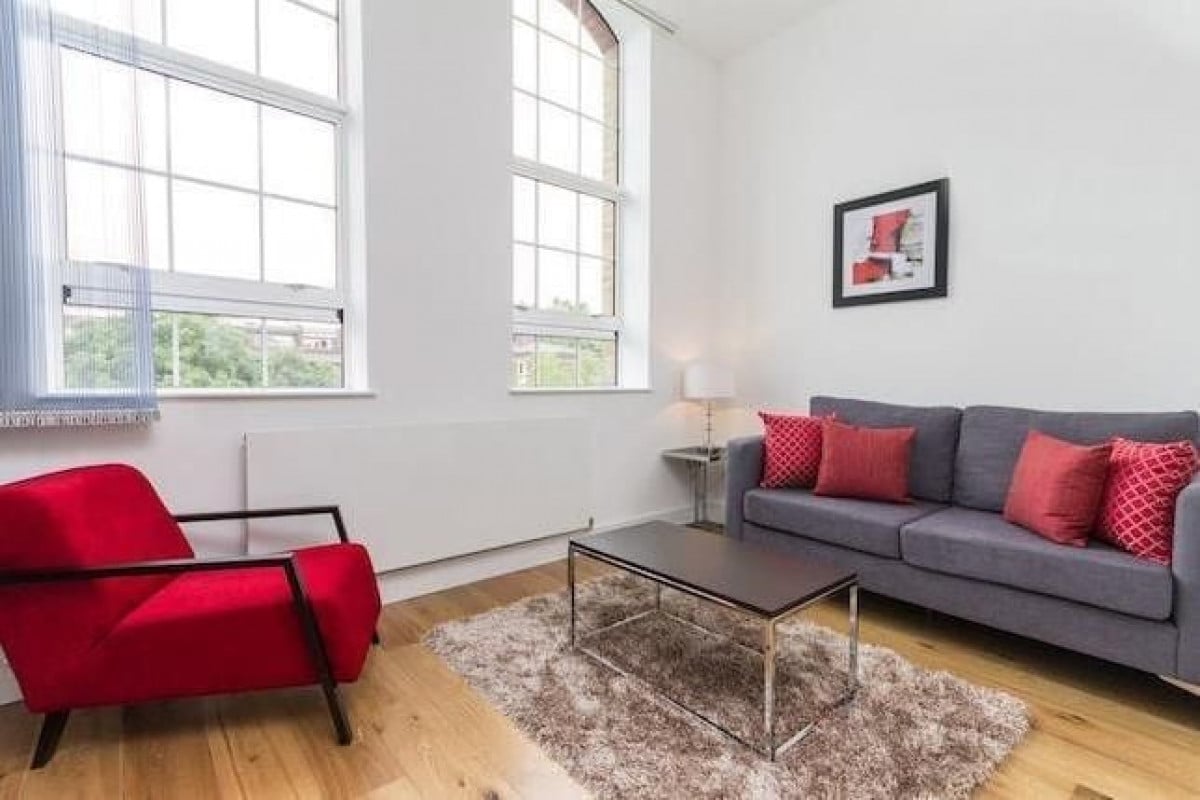
Picture is from a stunning studio apartment in one of South London's most enviable locations available to buy September 2024. For the full listing please click here.
UK House Prices Stall in Autumn 2026: What Does This Mean for Sellers?
12.10.2026UK house prices stalled in September 2026. Discover what the latest figures mean for sellers and how to price your home in today's property market.
When Did Private Landlords Become an Extension of the State?
08.10.2026
UK Rents in 2026: Where Are Prices Rising Fastest?
07.10.2026
Sell or Let Your Property Online: Stay in Control with Emoov
23.09.2026Selling or letting a property no longer has to mean handing over thousands of pounds to a traditional estate agent.
Update: Emoov Is Staying on Rightmove
15.09.2026An update from Nick Neale, Director of Emoov, on our decision to stay on Rightmove and what it means for our customers.
Rightmove vs Zoopla vs OnTheMarket: Which Property Portal Is Best?
09.09.2026


The legal stuff
Emoov is a trading name of Griffin Residential Limited. Griffin Residential Limited is a company registered in England and Wales. Company Reg No. 09362284.