UK Government Announce Measures to Support Mortgage Holders
On 22nd June 2023, the Bank of England raised the interest rate to 5%, the highest level in 15 years, in an effort to curb inflation. Despite a raft of interest rate rises, inflation currently stands at 8.7% - a statistic which is worryingly much higher than the ideal target of 2%. With homeowners feeling the squeeze more than ever, the rise in interest rates is likely to have a significant impact on mortgage costs and leave some households struggling to pay their bills.
It may seem strange to raise interest rates and further impact people's pockets. However, as interest rate rises make borrowing more expensive and reduce the demand for products, businesses have less money to spend and price rises begin to taper off. While interest rate rises are concerning in the short term, the hope is that in the long term the economy will stabilise.
However, with homeowners trying to navigate their way through the current cost of living crisis, the UK government has recognised that some steps must be taken to support them in the meantime.
Mortgage Deals at Over 6%
Homeowners coming to the end of fixed rate deals may find that the hike in their repayments are beyond their reach, leading to heightened stress and anxiety as they attempt to keep roofs over their families' heads. It is inevitable that repossession rates will increase as a result of the rise.
On 23rd June, in collaboration with mortgage lenders, Chancellor Jeremy Hunt announced a raft of measures to try to avoid this unfortunate scenario.
- Repossession holiday
First and foremost, the government has announced a crucial 12 month grace period for those facing difficulties in making repayments, starting from the date of the first missed payment. This grace period will allow lenders to support their customers and hopefully avoid repossession.
Agreed following consultation with mortgage lenders such as Lloyds Bank, NatWest and Barclays, it should be noted that the repossession holiday will only apply to 75% of lenders, leaving some homeowners vulnerable.
- Mortgage payment break
Those struggling to make repayments may be able to take a break from paying the mortgage or reduce the size of the payments for a short period of time. This flexibility also allows mortgage holders to switch back to their previous terms afterwards.
- Protected credit scores
Crucially, the government has announced that homeowners will be able to move to an interest-only mortgage deal for up to six months without impacting their credit scores. There is also the option to extend the length of the mortgage repayment term; for example, extending it from a 25 year plan to a 30 year plan. This will reduce the size of the repayments.
- Ability to agree to a fixed rate deal ahead of time
Homeowners will now have the opportunity to research and select fixed rate deals six months before their current deal ends. Most importantly, they will not be tied in to a contract and can switch to a better deal if one becomes available.
Are There Any Concerns Over These Measures?
Whilst these steps are a positive move for homeowners, some believe that the UK government should have gone further and agreed a financial support plan. Tory backbenchers as well as opposition parties have criticised the measures, saying that they are too weak and do not go far enough to support mortgage holders.
Financial lenders are expected to have these plans in place by 30th June. However, companies are facing a monumental task to study the initiatives and work out the details before offering them to mortgage holders. This may result in a delay in homeowners being able to access the new measures.
With homeowners feeling the pinch in the aftermath of the Covid-19 pandemic and struggling to cope as a result of the cost-of-living crisis, it's crucial that they are given adequate support to ensure they can keep their homes. It remains to be seen whether these initiatives will be sufficient to ease the pressure, but most importantly, mortgage holders should endeavour to be open and transparent with financial lenders so they can receive valuable assistance.
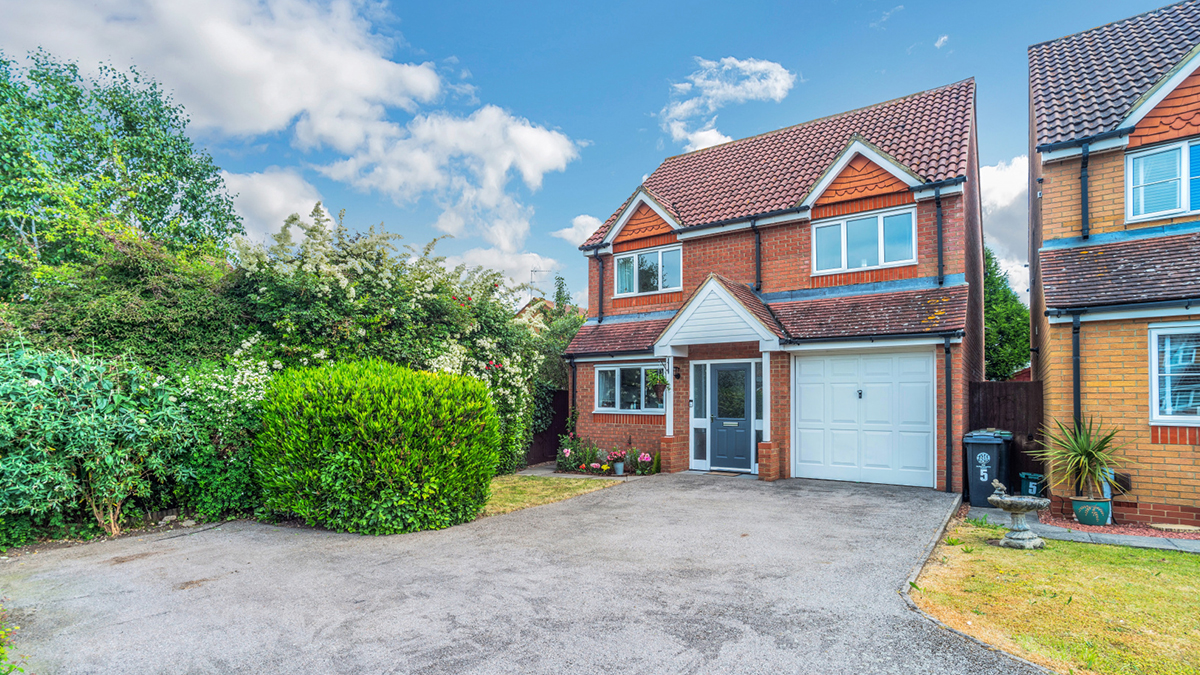
Image is from a sold 4 bedroom property located in Rushden. For the full listing, please click here.
UK House Prices Stall in Autumn 2026: What Does This Mean for Sellers?
12.10.2026UK house prices stalled in September 2026. Discover what the latest figures mean for sellers and how to price your home in today's property market.
When Did Private Landlords Become an Extension of the State?
08.10.2026
UK Rents in 2026: Where Are Prices Rising Fastest?
07.10.2026
Sell or Let Your Property Online: Stay in Control with Emoov
23.09.2026Selling or letting a property no longer has to mean handing over thousands of pounds to a traditional estate agent.
Update: Emoov Is Staying on Rightmove
15.09.2026An update from Nick Neale, Director of Emoov, on our decision to stay on Rightmove and what it means for our customers.
Rightmove vs Zoopla vs OnTheMarket: Which Property Portal Is Best?
09.09.2026


The legal stuff
Emoov is a trading name of Griffin Residential Limited. Griffin Residential Limited is a company registered in England and Wales. Company Reg No. 09362284.